If you started building a nest egg in your 40s or 50s, a free planner can measure your retirement gap in minutes and map the contributions that could close it before the final paycheck.
In this Insiderbits guide, we’ll introduce Empower, the platform that tests those balances against recessions, turning projections into a savings target that fits the years you’ve got left.

4.8/5
Which is the app to run a retirement gap diagnostic for late starters?
Empower (Android | iOS) is a platform that tracks your net worth by gathering investments, cash, credit cards, and loans in one dashboard, showing what you own and what you owe.
Its Retirement Planner projects your savings against spending goals and income sources and shows whether a retirement gap needs your attention before you commit to new contributions.
Empower also administers 401(k), 403(b), and 457 plans, welcomes accounts from other financial firms, and puts your employer balance and your outside holdings on one shared view.
Key features within Empower
- Portfolio analysis: flags allocation imbalances across your investment accounts and shows where your next contribution could restore balance to your preferred asset mix;
- Budgeting and cash flow: charts money moving in and out of your accounts and lets you set budgets that measure your spending against limits you choose;
- Debt paydown: builds a payoff plan for card balances and loans, trimming what you owe and giving your credit score room to climb as totals shrink;
- Emergency fund: estimates the cash cushion your household needs for life’s curveballs, giving you a ready reserve you can tap before you draw down your portfolio.
Tools that fit a shorter savings runway
When the runway is short, every assumption matters, and the planner lets you adjust inputs and compare scenarios side by side until you find a plan your income can fund.
Investors who hold $100,000 in assets can book a call about ‘Personal Strategy’, which is a fee-based service that pairs you with a financial advisor and a team of specialists.
Keep your numbers private from start to finish
Empower (Android | iOS) shields the personal financial details you share with encryption, multifactor authentication, fraud protection, and biometric login, which replaces password typing.
You can run your retirement gap diagnostic without any advisor on the line, and the platform lets you request deletion of your stored data if you decide to quit their services.
Step-by-step: how to calculate your retirement gap in the app
Calculating a shortfall in Empower (Android | iOS) means subtracting two numbers: what your savings can fund and what you expect to need, and the platform handles the arithmetic for you.
Write down your birth year, the age you hope to stop working, and a rough monthly cost of living before you begin, as those inputs determine every result you’ll see.
The planner’s readiness estimate points to your retirement gap once the monthly cost of living you wrote down enters the calculation, and any change to your inputs reshapes the result.
Step 1: download the app or use the website
Unlock your device and search for ‘Empower’ on the Google Play or the App Store. Hit ‘Install’ or ‘Get’ and wait a few seconds until the app shows up on your home screen.
If you’d rather use your computer or laptop, open the Empower website in your browser and head to the top right corner of the homepage, then click the ‘Open an account’ button.
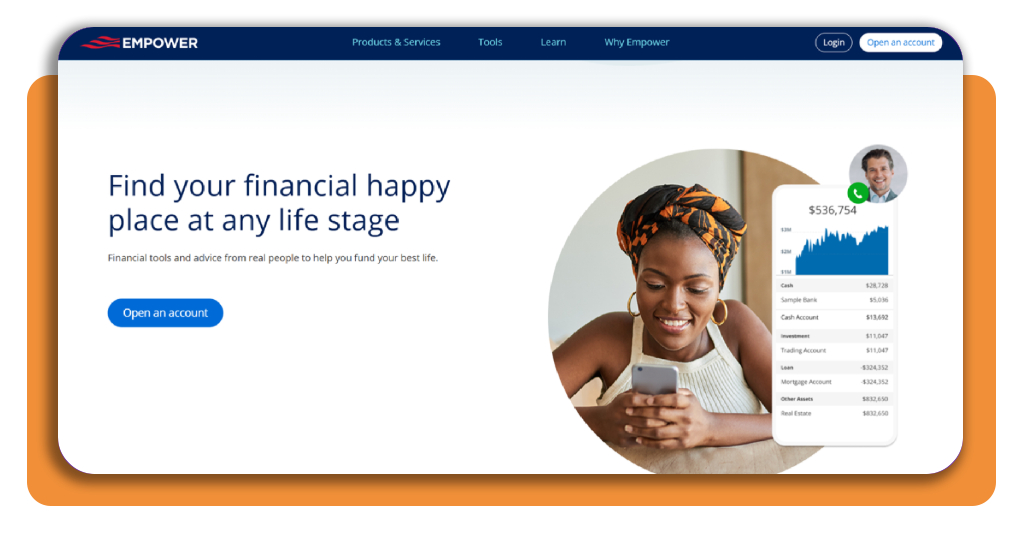
Step 2: choose what you’re looking for
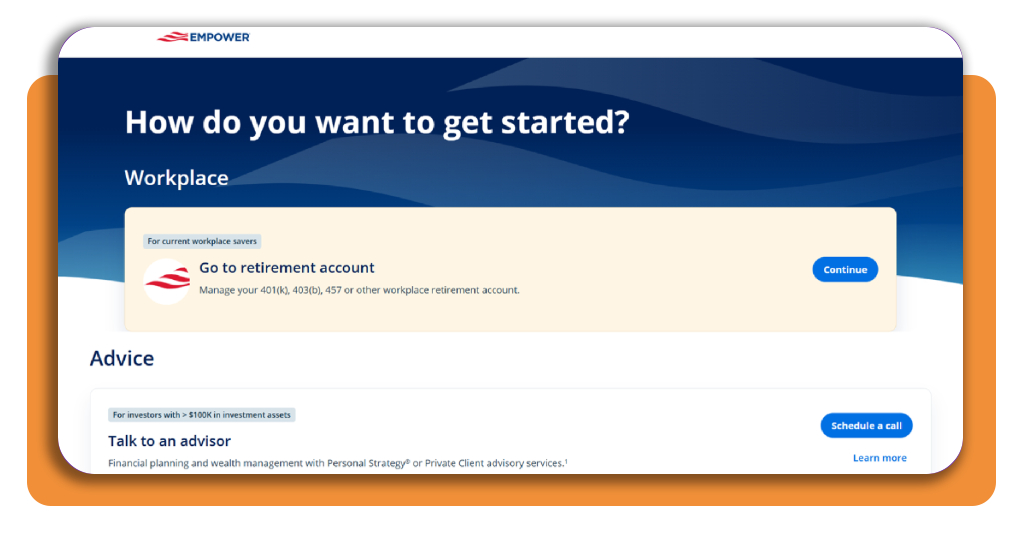
The ‘How do you want to get started’ screen opens with a ‘Workplace’ section at the top, and its beige card carries a small gray tag for current workplace savers.
Click the blue ‘Continue’ button on the right side of the ‘Go to retirement account’ card, which is the option for managing your 401(k), 403(b), 457 or any other workplace retirement account.
Step 3: create and connect all your accounts
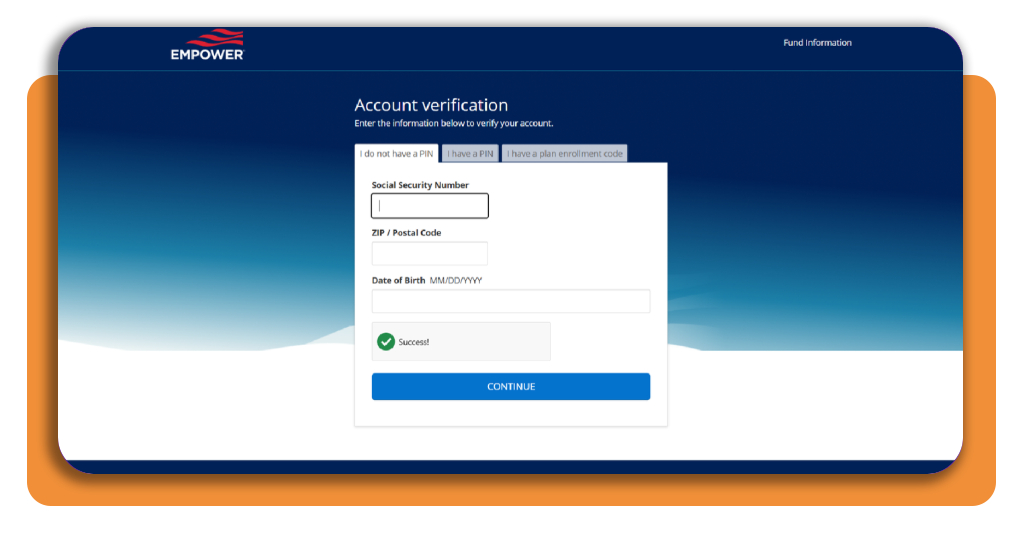
Create your account on the ‘Account verification’ page by entering your Social Security number, ZIP code, and date of birth, then click the ‘Continue’ button to reach the next screen.
After verification, link all your banks, IRAs, old employer plans, and mortgages to the platform. A missing balance will distort your retirement gap by hiding savings or overstating your assets.
Step 4: open the Retirement Planner and compare scenarios
Open the ‘Tools’ menu on the website, choose ‘Retirement Planner’, and place major life events such as a home remodel on the timeline to anchor the results to your plans.
Then test different retirement ages, such as 62 and 67, and watch the numbers respond, and compare retiring early with continuing to work until one scenario fits your budget.
Top wealth management firms
Empower (Android | iOS) shows you how far your savings fall from your goals, and a wealth management firm takes over by assigning a professional to build the plan that closes the distance.
Firms differ in how they charge, whom they serve, and what minimum balance they expect from new clients, and those differences narrow your list before you book a first conversation.
HB Wealth, Range, and Ellevest all start from the numbers you gathered, and they address your retirement gap through different mixes of planning, tax advice, and investment management.
HB Wealth delivers fiduciary advice since 1989
HB Wealth began in 1989 as Homrich Berg, and its fee-only fiduciary model means advisors earn from your fees and carry a legal duty to put your interests first.
The firm keeps offices in 7 states, serves clients in 49, and focuses on high-net-worth, including executives with stock options and business owners planning a company sale.
Range offers planning with no asset minimums
Range bills a flat membership fee with no percentage of your assets and no minimum balance, and new members finish the intake covering goals and accounts in about 20 minutes.
Premium covers core planning, Platinum adds tax projections and estate documents, and Titanium adds tax filing, while a team of certified planners answers your questions.
Ellevest focuses on women building wealth
Ellevest builds its practice around women, with full wealth management starting at $500,000 in investable assets and standalone financial planning available for a flat $3,600 per year.
If caregiving costs or a divorce widened your retirement gap, Ellevest advisors weigh those life events in your plan alongside tax loss harvesting, equity compensation, and private alternatives.
Best options for maximizing catch-up limits
Starting at 50, you can contribute extra dollars to workplace plans and IRAs beyond the standard limits, and your Empower (Android | iOS) results point to how much of that room you need.
Raising your annual contributions is one lever, and the investments you pick and the accounts that hold them decide how much of that money survives taxes and sharp market swings.
Late starters can lean on these allowances to narrow a retirement gap that felt fixed at 45 or 50, and smart investment choices give every added dollar a productive job.
Super catch-up limits for ages 60 to 63
In 2026 a 401(k) deferral tops out at $24,500, up $1,000 from 2025, and savers 50 and over add $8,000, lifting the ceiling to $32,500 before counting any employer match.
Ages 60 through 63 add $11,250 for a $35,750 total, but IRAs skip that tier and allow savers $1,100 extra, and the 401(k) limit returns to $32,500 at age 64.
Match your stock mix to your age
Planners start with a simple formula that subtracts your age from 100 or 120 to set your stock share, placing a saver who’s 63 between 37% and 57% in stocks.
Send extra contributions into low-cost stock and bond index funds or a target-date fund, and skip losses that would widen your retirement gap with little time to recover.
Put bonds and index funds in the right accounts
Place bonds and mutual funds inside your 401(k) or IRA, and reserve your taxable brokerage account for broad stock index funds and individual stocks paying qualified dividends.
Stocks you hold for years escape tax until you sell and qualify for favorable long-term capital gains rates, while interest and short-term trading profits face ordinary income rates.
4.8/5
Your retirement math finally adds up
Empower (Android | iOS) takes what you’ve saved, lines it up against the retirement you picture, and shows you whether the money stretches that far through a free account you control.
In this Insiderbits guide, you learned exactly how to measure your retirement gap, find advisors who fit your budget, and put extra savings to work in the right accounts.
Keep browsing Insiderbits for guides and reviews that turn confusing choices into decisions you can talk through with your family, and browse more articles on making your savings last.