For public employees, corporate veterans, and union members holding defined-benefit plans, executing a pension maximization plan is one of the most effective ways to increase lifelong retirement payouts.
Rather than default to reduced survivor annuity options offered by plan administrators, retirees can optimize their monthly cash flow while keeping full financial protection intact for family members. Read on Insiderbits.

4.2/5
Which is the app to maximize Social Security and pension benefits?
When retiring, workers typically must choose between a single-life payout or a joint-and-survivor payout (which permanently reduces monthly benefits by 15% to 30% to extend income to a surviving spouse).
A pension maximization strategy creates a tax-free death benefit for the spouse while maximizing lifetime income during retirement.
When planning a model, combining pension timing with Social Security claiming strategies yields the highest net lifetime benefit.
Deciding whether to claim Social Security at age 62, Full Retirement Age (FRA), or delay until age 70 directly influences how much private life insurance coverage is needed to protect a spouse.
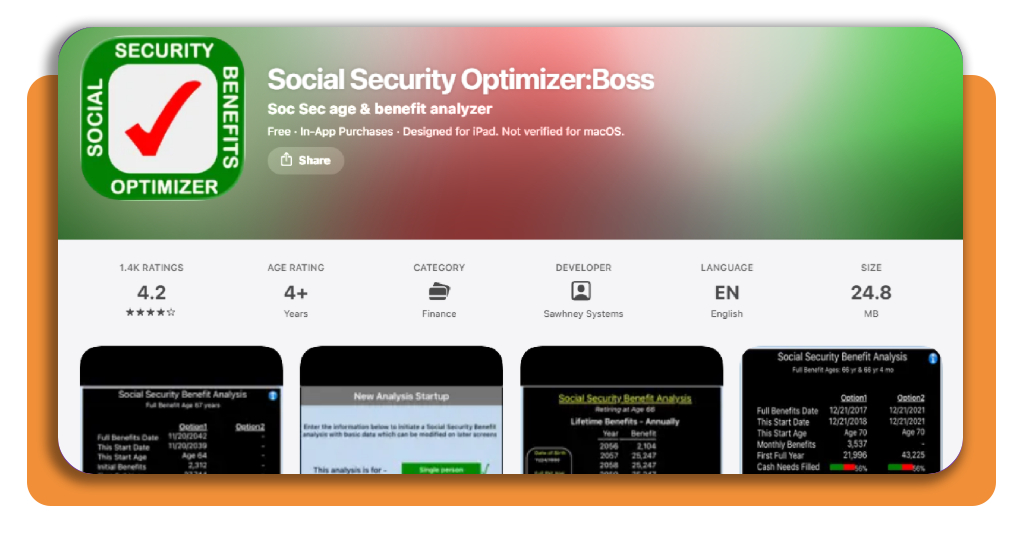
The Social Security Optimizer: BOSS app (developed by Sawhney Systems) evaluates marital status, life expectancies, COLA projections, and income tax brackets.
Available for Android and iOS, the app calculates exact break-even points between claiming early versus delaying benefits.
Using this tool alongside private pension estimates helps pre-retirees model exact monthly cash flows before committing to irrevocable election forms.
Key features within the Social Security Optimizer platform
- Break-even analysis: calculates the precise age at which delaying Social Security or adjusting pension elections yields higher cumulative lifetime cash flow;
- Dual-profile married couple modeling: evaluates joint spousal claiming scenarios, survivor benefit rules, and spousal top-offs to maximize total household safety nets;
- Income tax and inflation impact projections: simulates how federal income tax brackets and annual Cost-of-Living Adjustments (COLA) modify net retirement purchasing power over 30+ years;
- Minimal data input requirements: generates tabular and graphical reports using simple inputs like birth date and primary insurance amount (PIA);
Step-by-step: how to calculate your maximum retirement payout
Executing a successful pension maximization strategy requires careful math, underwriting verification, and coordination between pension administrators and insurance carriers.
Because pension election choices are legally irrevocable once payments begin, taking a disciplined step-by-step approach prevents costly mistakes.
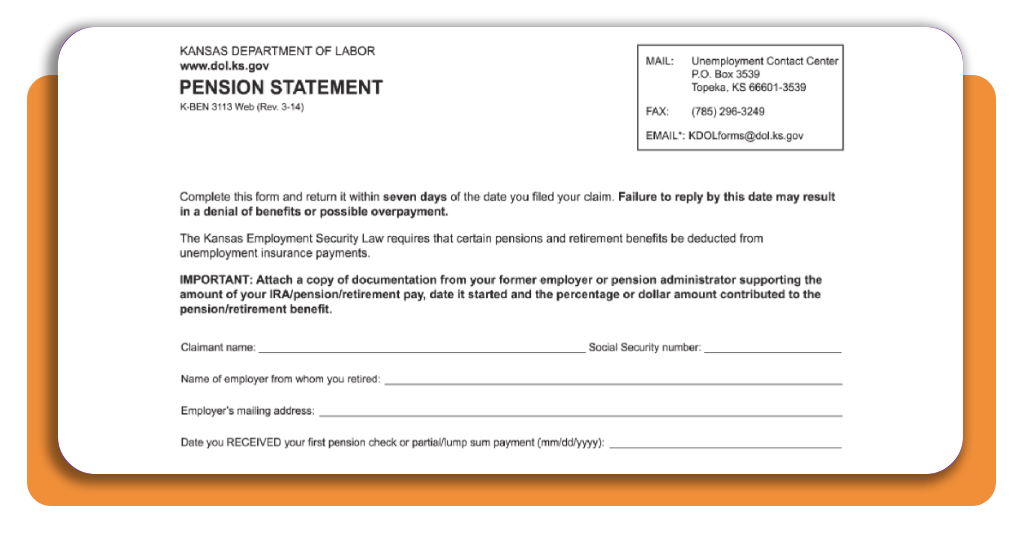
Step 1: obtain pension option estimates
Request a formal pension benefit statement from your human resources department or pension administrator.
Document the exact monthly dollar amounts for the 100% single-life payout and various joint-and-survivor options (such as 100%, 75%, and 50% survivor benefits).
Step 2: calculate the monthly benefit gap
Subtract the joint-and-survivor monthly amount from the single-life monthly amount.
The difference represents the cost your pension administrator charges to provide a survivor benefit. This gap defines your maximum monthly budget for private life insurance under a pension maximization framework.
Step 3: apply for and underwrite permanent life insurance
Before signing pension papers, apply for a permanent life insurance policy (such as Whole Life or Guaranteed Universal Life) with a death benefit large enough to generate equivalent survivor income.
Ensure the policy is fully approved and in force before electing the single-life pension payout option.
Step 4: model social security claiming ages
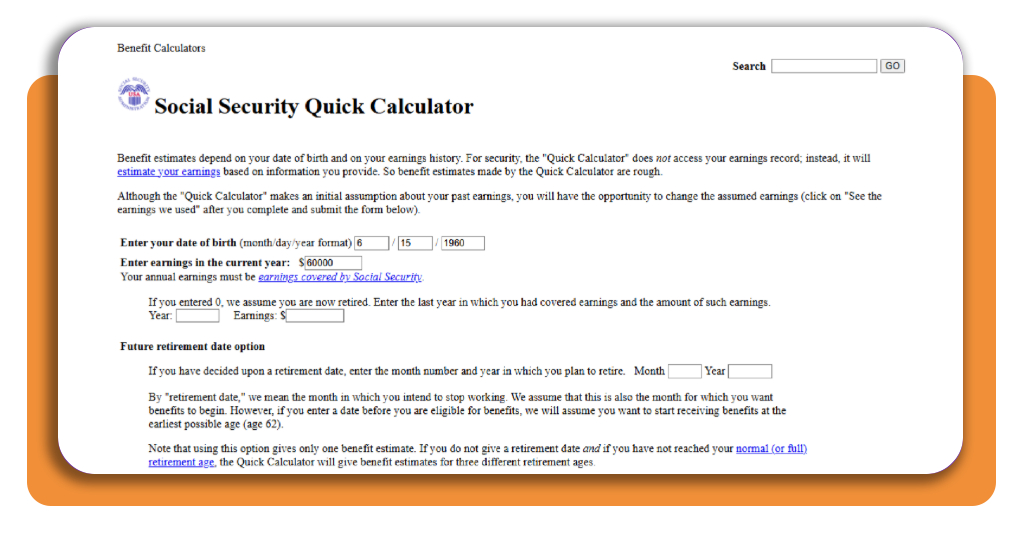
Use the official Social Security Quick Calculator or the BOSS app (iOS | Android) to determine your optimal claiming age.
For individuals working without a Social Security Number who are building independent tax records, an ITIN application guide helps clarify tax filing and asset accumulation options.
Step 5: finalize pension selection and coordinate cash flow
With permanent life insurance active, formally select the single-life pension option in your pension maximization plan.
Complete required notarized spousal waiver forms, set up automated payments from your higher monthly pension check, and allocate residual cash surpluses into liquid savings.
Top retirement planning tools
While specialized software helps analyze pension election nuances, incorporating broader financial management applications strengthens your overall pension maximization strategy.
Software suites assist in tracking multi-asset portfolios, monitoring spending habits, and running Monte Carlo simulations across market cycles.
Empower (Personal Capital)
Empower offers free wealth management tools featuring a dedicated Retirement Planner.
It aggregates investment accounts, models cash flow projections, and simulates market stress tests to determine if your single-life pension and investment portfolio can sustain long-term inflation.
Boldin (formerly NewRetirement)
Boldin is built specifically for comprehensive retirement income planning.
It allows users to model complex scenarios, including pension options, Social Security strategies, Roth conversions, healthcare expenses, and real estate equity, making it ideal for self-directed planners.
ProjectionLab
ProjectionLab provides visual financial modeling for pre-retirees and early retirement enthusiasts.
Its granular cash flow engine makes it easy to compare a standard survivor pension against a pension maximization model paired with life insurance cash values over a 40-year timeline.
Best high-yield savings accounts
A fundamental component of executing a pension maximization strategy is maintaining an accessible cash buffer.
Holding six to twelve months of living expenses in cash protects retirees from having to sell equity investments during market downturns or during the transition period between active work and pension initiation.
To earn competitive returns on liquid emergency reserves, review financial benchmarks for the high-yield savings accounts available today:
Marcus by Goldman Sachs
Marcus offers a top-tier high-yield savings account featuring competitive APYs, zero monthly maintenance fees, and no minimum deposit requirements.
Its transfer tools make it a reliable home for liquid retirement reserves supporting your pension maximization timeline.
Ally Bank
Ally Bank combines competitive interest rates with ‘Savings Buckets’ that allow retirees to categorize cash reserves into separate allocations—such as insurance premium reserves, home maintenance funds, and travel budgets.
SoFi Bank
SoFi provides high-yielding savings accounts with direct deposit features, zero account fees, and FDIC insurance coverage up to $2 million through sweep networks, ensuring high liquidity and security for large balances.
4.2/5
Optimizing your pension payout
Implementing a well-structured pension maximization strategy empowers retirees to unlock maximum monthly cash flow while keeping their surviving spouse fully protected.
Time to build a resilient financial legacy that lasts throughout your retirement years.