Understanding Social Security for immigrants requires unpacking how work credits, legal residency statuses, and guidelines from the SSA non-citizens resource dictate benefits.
Whether you are a recent arrival or have spent decades building a career in the U.S., mapping out your retirement requires a clear approach. Read it on Insiderbits.

4.8/5
Unlocking international work history
For many immigrants, building the mandatory 40 work credits (roughly equivalent to 10 years of covered U.S. employment) required for full retirement benefits can feel challenging if a portion of their career was spent abroad.
To prevent workers from losing credit for contributions made in multiple nations, the United States has established bilateral treaties known as Totalization Agreements with approximately 30 countries.
These international pacts serve a dual purpose:
They eliminate dual social security taxation when professionals move temporarily for work, and allow workers to combine credits earned overseas with those earned on U.S. soil to meet minimum retirement eligibility thresholds.
While your actual monetary credits do not physically transfer across accounting systems, each agency reviews your combined work history to calculate a proportional benefit.
Researching whether your home country maintains an active agreement with the Social Security Administration can unlock vital financial support that might otherwise remain out of reach.
Which is the best app to project Social Security for immigrants?
Planning for retirement when your career history spans multiple countries or includes varying legal statuses requires robust digital tools.
Financial dashboards help immigrants aggregate multiple accounts, track net worth, and model projected U.S. retirement milestones.
Among digital financial management platforms, the Empower app (available on the iOS App Store and the Google Play Store) stands out for consolidating fragmented financial data.
Key features within Empower
- Comprehensive net worth tracking: syncs checking accounts, investment portfolios, and retirement vehicles in one place to give you a complete picture of your financial health;
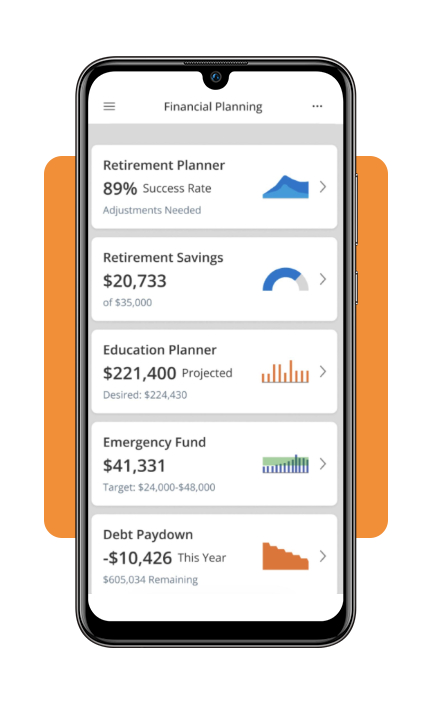
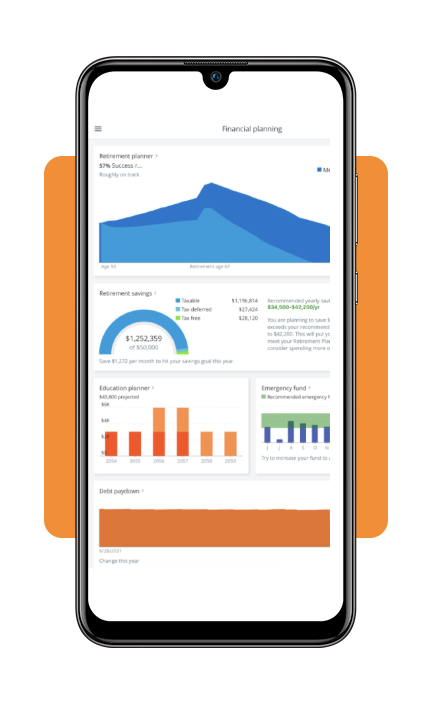
- Interactive retirement planner: lets you simulate different retirement ages, inflation rates, and lifestyle expenses to see if your savings and projected Social Security for immigrants benefits will suffice;
- Cash flow analysis: tracks monthly spending and saving habits, helping you allocate more funds toward tax-advantaged retirement accounts during peak earning years.
Step-by-step: how to model a Social Security scenario
Navigating the United States retirement system can be complex, and for foreign-born workers, the challenge is compounded by specific immigration, tax, and work authorization rules.
Projecting your future retirement benefits accurately ensures you can bridge any financial gaps before leaving the workforce. Check the following steps:
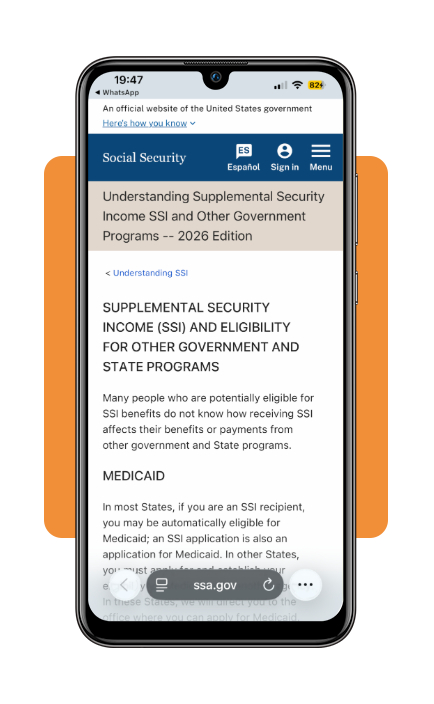
Step 1: access your social security statement
Log into your official online account with the Social Security Administration to verify your accumulated work credits and reported earnings history.
Step 2: connect your accounts in Empower
Link your bank accounts, 401(k) plans, and individual retirement accounts to the Empower dashboard on your iOS or Android to track your total assets in real-time.
Step 3: input projected income and retirement age
Use financial calculators to factor in your estimated future earnings and determine how retiring at age 62, full retirement age (67), or age 70 affects your monthly payout.
Step 4: plan for supplemental savings
Compare your projected total income against estimated living expenses to see if you need to increase private retirement contributions.
Top immigration law firms and services
Securing your eligibility for federal benefits begins with maintaining proper legal status and a valid Social Security Number (SSN) tied to work authorization.
Complex visa transitions, green card renewals, or path-to-citizenship applications can profoundly impact your long-term legal and financial standing in the United States.
Below, we curated a list of leading immigration law firms and national services recognized for their legal expertise:
- Fragomen, Del Rey, Bernsen & Loewy, LLP: Fragomen is widely recognized as a global leader in corporate and individual immigration services, handling everything from complex visa petitions to family-based compliance;
- BAL (Berry Appleman & Leiden LLP): BAL is a premier firm focusing entirely on corporate and individual immigration, known for pioneering technology-driven global mobility solutions and end-to-end case management;
- Greenberg Traurig, LLP: Greenberg Traurig is a major international multi-practice firm featuring a dedicated immigration and compliance group with extensive experience across employment, investor, and family-based immigration;
- Wolfsdorf Rosenthal LLP (WR Immigration): Wolfsdorf Rosenthal is regarded for handling complex business immigration, investor visas, and individualized legal status adjustments;
- Klasko Immigration Law Partners, LLP: Klasko Law is noted for legal excellence in employment, family, investment, and institutional immigration support.
And for the ones seeking accessible legal guidance, community resources and guidance on legal aid for immigrants provide stepping stones to ensure your documentation remains compliant with federal standards.
Best options for maximizing retirement contributions
Relying solely on Social Security benefits rarely covers all living expenses in retirement, making supplemental savings needed—especially for immigrants who may have started building U.S. work histories later in life.
To accelerate your wealth accumulation during peak earning years, financial educators recommend fully utilizing tax-advantaged accounts.
Understanding Social Security for immigrants is only one piece of a broader retirement strategy. Key savings vehicles include:
- Employer-sponsored 401(k) plans: take full advantage of employer matching contributions, which represent free money that accelerates your portfolio growth;
- Traditional and Roth IRAs: open individual retirement accounts to diversify your tax liabilities in retirement;
- Catch-up contributions: once you reach age 50, utilize allowable catch-up contributions to ramp up annual savings in both 401(k)s and IRAs.
4.8/5
Planning ahead makes a difference
Understanding how Social Security for immigrants works can help you make more informed decisions about your long-term finances in the United States.
Keeping your records up to date, monitoring your earnings history, and verifying that your work credits are being reported correctly are important steps toward qualifying for future benefits.
Tools like the SSA online portal and retirement planning apps can make it easier to track your progress and estimate future income.
Combined with personal savings and retirement accounts, Social Security for immigrants can become one part of a broader strategy for building financial security over time.